
 1 hour ago
12

Strategy’s Bitcoin purchase came with a bigger transaction hiding in plain sight. Michael Saylor’s company bought about $82 million of BTC last week while spending approximately $188 million repurchasing its STRC preferred shares. The balance between those two uses of money tells investors more than another headline about an expanding coin pile.
The November 9 disclosure reports 1,036 BTC acquired between November 2 and November 8, bringing holdings to 850,364 BTC. But the most revealing comparison is the amount devoted to preferred-share repurchases: roughly 2.3 times the Bitcoin expenditure.
Where the money went
Strategy raised $283.8 million net through sales of about 2.05 million MSTR common shares. Of those proceeds, $81.9 million funded Bitcoin purchases, $188.3 million funded STRC repurchases, and $13.6 million was allocated to USD Cash.
The source of funding matters. The filing explicitly connects these repurchases to new common-stock sales. It would be misleading to describe the transaction as an ordinary buyback in which a company simply reduces its common-share count using surplus operating cash.
Instead, the company issued one security while repurchasing another. Existing ordinary shareholders therefore need to consider both sides: the effect of additional MSTR shares and the benefit of reducing the preferred securities outstanding. More Bitcoin is only one part of that calculation.
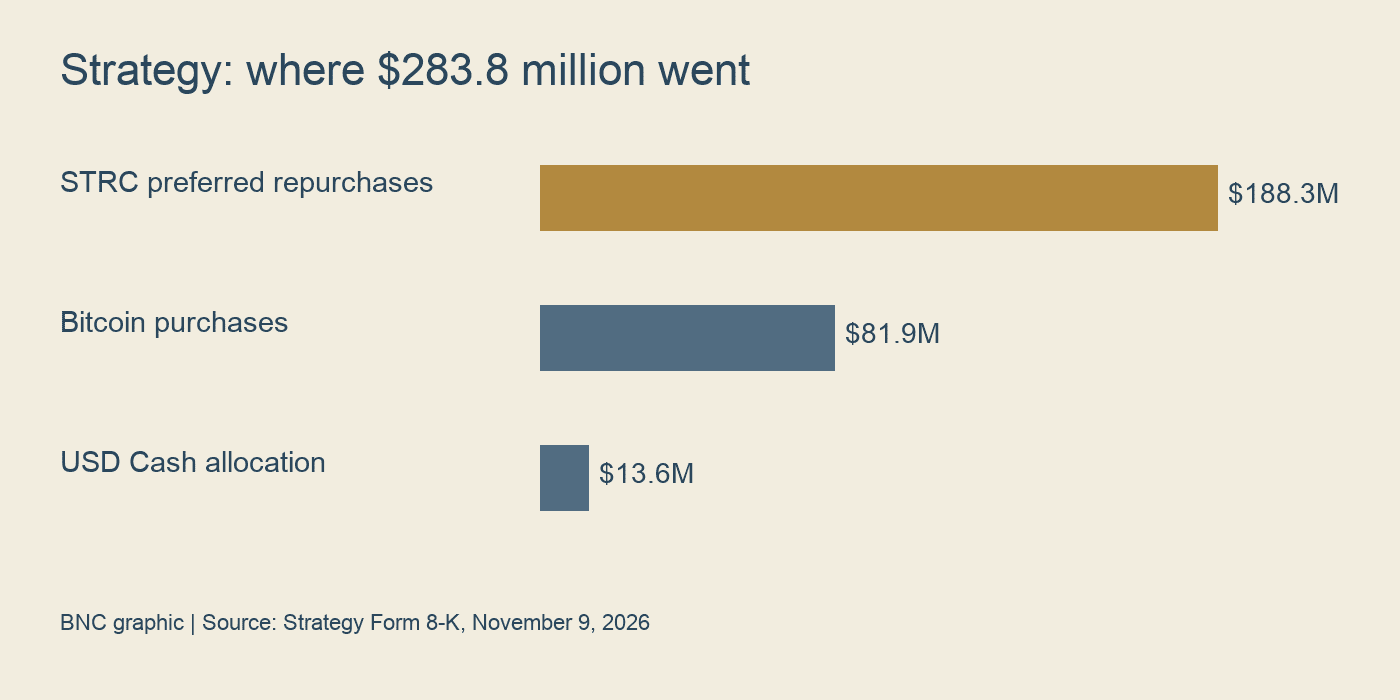 BNC chart from Strategy’s November 9 Form 8-K, linked above. Net MSTR sale proceeds allocated during November 2–8, 2026.
What STRC changes about the story
STRC is Strategy’s variable-rate perpetual preferred stock, which the company markets as Stretch. Its STRC dashboard displays its price, dividend rate and other measures separately from those of MSTR. The distinction is fundamental: a preferred instrument and an ordinary share offer different claims and exposures.
Repurchasing preferred shares can reduce the amount of capital carrying a preferred dividend obligation. That can be attractive even when management remains committed to Bitcoin accumulation. It also means that the number of coins bought in a particular week is an incomplete measure of what management accomplished or prioritised.
This is an interpretation of the financing mechanics, not proof that Strategy has abandoned its Bitcoin thesis. The company continued buying BTC during the same reporting period. The useful question is how management balances accumulation against the cost and structure of its funding.
For an MSTR holder, a larger Bitcoin treasury is not automatically the same thing as a proportionately larger economic interest in that treasury. Issuing common stock changes the denominator. Any assessment of progress needs to consider the claims ahead of common shareholders as well as the assets behind them.
The purchase price is not a liquidation trigger
The newly acquired coins cost an average $79,012 each, including fees and expenses. Strategy reported an average acquisition price of $75,456 across its holdings and an aggregate purchase price of about $64.16 billion.
Those figures describe historical acquisition costs. They do not, by themselves, establish a price at which the company must sell Bitcoin, a margin call must occur or shareholders are guaranteed a particular return. Market commentary that turns an accounting average into an automatic liquidation line skips the financing terms that would actually govern such an event.
There is still a real economic sensitivity. As a simple illustration, a $1,000 move in Bitcoin changes the gross market value of 850,364 coins by approximately $850 million. That arithmetic ignores taxes, other assets, liabilities and changes in the share count; it is a scale comparison rather than a valuation model.
BNC’s Bitcoin CPI preview examines the separate macro forces affecting crypto markets. For Strategy investors, those market forces interact with financing choices that are specific to the company.
Cash matters alongside the coins
The filing describes a dollar reserve intended to support “dividends on Strategy’s preferred stock and interest on its outstanding indebtedness.” It reported $4.77 billion in that reserve and $146.2 million in USD Cash as of November 8.
Those balances serve different stated purposes, so combining them into one undifferentiated cash figure obscures management’s framework. Nor should a reserve balance be treated as a permanent guarantee: obligations, financing access and future decisions can change.
The important analytical distinction is between owning an asset that may appreciate and maintaining the cash needed to service a capital structure. Bitcoin does not pay a contractual cash dividend to its holder. A treasury company therefore needs an explicit way to meet cash commitments while pursuing a long-term asset strategy.
What the next disclosure should reveal
Investors can test the direction of travel by comparing future filings on a consistent basis. How much fresh equity is issued? How much goes into BTC? How much retires preferred stock? And how do the reserve balances change alongside those decisions?
A single week cannot establish a permanent shift. A sustained pattern would be more informative, particularly if preferred repurchases repeatedly absorb more funding than new Bitcoin purchases. That would make capital management an increasingly central part of understanding the business.
The latest update shows continued accumulation alongside substantial restructuring of the securities that finance it. Saylor’s Bitcoin conviction remains visible in the purchases. For shareholders, the harder and more useful question is what each additional dollar raised ultimately delivers after the cost of funding is taken into account.


 Bengali (Bangladesh) ·
 English (United States) ·