 4 hours ago
5

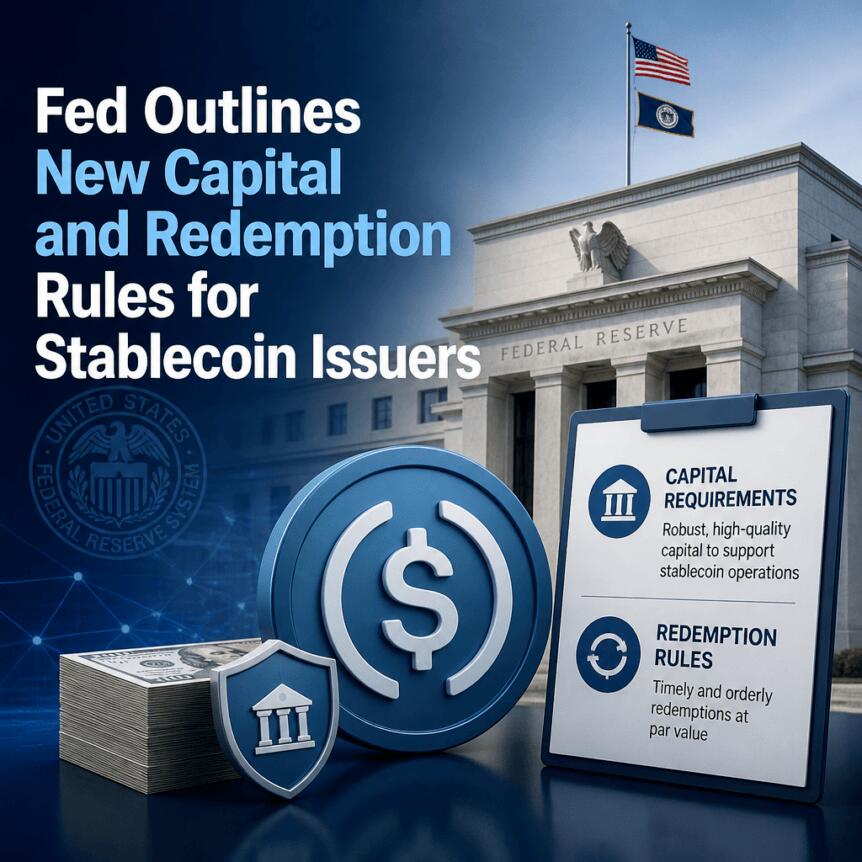
The Federal Reserve has released proposed rules aimed at tightening oversight of stablecoin issuers as the U.S. works to implement the GENIUS Act. The proposals set out how Fed-supervised entities would be required to hold reserves, manage risk, handle redemptions, and report key information about their stablecoins.
While the GENIUS Act already mandates that stablecoins be backed on a one-to-one basis with specified reserve assets, the Fed’s plan would add more granular requirements—especially around capital levels tied to operational risk, credit-related risks, and standardized reporting and assurance.
Key takeaways
The Fed’s proposal would require operational-risk capital charges for stablecoin issuers, scaling based on the amount of stablecoins outstanding. Issuers would generally need to process redemptions within two business days and notify the Fed if reserves fall below required one-to-one backing. Monthly reserve and outstanding stablecoin reporting would be required, with disclosures examined by a registered public accounting firm and certified by the issuer’s CEO and CFO. A separate Fed proposal would create a pathway for Fed-supervised banks to seek approval to issue payment stablecoins through subsidiaries. Fed Governor Michael Barr supports the direction of the framework but says stablecoin reliability during market stress still needs further work.What the GENIUS Act already requires—and what the Fed is adding
Under the GENIUS Act, stablecoin issuers must maintain reserves backing their tokens on a one-to-one basis and can only hold certain types of assets. These include cash, bank deposits, and short-term U.S. Treasurys, among other permitted instruments. The law also assigns federal regulators the task of writing the more detailed capital, reserve-diversification, and risk-management rules.
According to the Fed’s published documents, the agency’s proposals are intended to translate those statutory requirements into day-to-day supervisory expectations for issuers under Fed oversight.
Operational-risk capital, redemptions, and reserve shortfalls
One central piece of the Fed’s proposal is a capital framework tied to operational risk. As outlined in the Fed’s plan, issuers would face an operational-risk capital charge calculated as follows: 2% of the first $20 billion in stablecoins outstanding, 1.5% of the next $30 billion, and 1% of amounts above $50 billion. In addition to that operational-risk charge, the proposal contemplates further capital requirements linked to credit and operational risks.
On liquidity and redemption mechanics, the proposal would generally require issuers to process redemptions within two business days. If an issuer’s reserves drop below the one-to-one backing threshold, the issuer would have to notify the Fed. The issuer would then need to either restore reserves under a remediation plan or liquidate the reserves and redeem outstanding stablecoins.
For investors and traders, these elements matter because they directly affect the feasibility of exiting a stablecoin position when market conditions deteriorate or when an issuer faces stress on its reserve composition and operational controls.
Monthly disclosures and external verification
The Fed’s proposal also emphasizes transparency and accountability. Issuers would be expected to publish monthly reports covering their outstanding stablecoin balances as well as the value and composition of reserves backing those tokens.
Those disclosures would not be limited to internal attestations. The proposals call for the disclosures to be examined by a registered public accounting firm, and for certification by the issuer’s CEO and CFO.
This structure—audited examination plus senior executive sign-off—could create stronger compliance incentives for issuers, while giving market participants more consistent and comparable information to evaluate reserve backing over time.
Bank participation through subsidiaries: a separate application framework
In addition to rules for stablecoin issuers, the Fed also released a separate proposal intended to establish an application process for Fed-supervised banks that want approval to issue payment stablecoins through subsidiaries.
As described in the Fed’s second proposal, banks would be required to submit a business plan and financial information as part of the approval process. The separate track suggests the Fed is attempting to clarify how regulated banks can participate in the stablecoin ecosystem while remaining within a defined supervisory structure.
Barr’s support, and the remaining reliability questions
Fed Governor Michael Barr backed the proposals on Thursday but argued that more work is needed before stablecoins can be considered reliable payment instruments. Barr said that “stablecoins will only be stable if they can be reliably and promptly redeemed at par in a range of conditions,” including during market stress, situations where even liquid government debt may come under pressure, and episodes of strain affecting a specific issuer or related entities.
In remarks tied to the Fed’s announcement, Barr indicated he was encouraged by proposed limits on reserve assets and by standardized capital requirements. At the same time, he urged public feedback on whether the framework adequately addresses interest-rate and foreign-currency risks.
Barr also raised questions about how universal redemption rights should be established in the final rule. He highlighted concern about an approach that could limit the Fed’s ability to take supervisory or enforcement action over an anti-money laundering deficiency unless the problem is deemed “significant or systemic.”
For market participants, Barr’s comments underscore a key tension: the rules aim to formalize backing and capital adequacy, but the final design will be judged on whether it holds up under real-world stress scenarios, not only in normal periods.
Public comment period and GENIUS Act implementation timing
The Fed’s proposals are open for public comment for 60 days after publication in the Federal Register, according to the Fed’s announcements. That comment window may determine how the capital formulas, redemption expectations, reporting requirements, and risk treatment ultimately look in final form.
The GENIUS Act is scheduled to take effect on Jan. 18, 2027, or 120 days after federal regulators issue final implementing rules, whichever comes first. As the rulemaking process advances, readers should watch how regulators refine stress-testing expectations, define the final contours of redemption rights, and decide how operational and financial risk controls translate into practical reliability for users.
This article was originally published as Fed Outlines New Capital and Redemption Rules for Stablecoin Issuers on Crypto Breaking News – your trusted source for crypto news, Bitcoin news, and blockchain updates.
 Bengali (Bangladesh) ·
 English (United States) ·